Written on 28 August, updated on 1 September 2026
Introduction: Lidl’s turnover has reached €179.4 billion, but Amazon is now the market leader in the sale of fast-moving consumer goods in Europe.
As we have previously reported, Lidl is focusing on artificial intelligenceand , building on a system created for internal use in 2021, the Schwarz Group – owner of Lidl – now offers cloud computing and cyber security services to third-party business clients.
Last year, the unit generated €1.9 billion in annual revenue and employs 7,500 staff…
It is now focusing on data centres:
The GermanSchwarzGroup, owner of the discount supermarket chainLidl, has announced that it will invest up to €5.6 billion ($6.5 billion) in adata centrein northern Germany, as part of a drive by European countries to reduce their dependence on foreign providers of cloud and artificial intelligence services.
Construction of the complex near the city of Rostock, which is expected to create 120 jobs, is due to begin in 2027, as announced at a press conference by Schwarz’s CEO, Gerd Chrzanowski, and the state’s Social Democratic Prime Minister, Manuela Schwesig.
By 2033, the data centre in the state of Mecklenburg-Western Pomerania will have a capacity of 240 megawatts, equivalent to the average energy consumption of 600,000 households, with the potential to expand capacity to 1 gigawatt by 2045, the German supermarket group stated in apress release…
Below: the owner, Dieter Schwarz.
A major project, certainly, but to understand the true scale of the AI race, as Massimo Giordani points out on LinkedIn, one need only look at the five largest American campuses already in operation or nearing completion:
Stargate in Abilene, Texas (OpenAI/Oracle), with a capacity of 1.2 GW, with the first buildings set to be operational from 2025 and completion expected by the end of 2026; Project Rainier in Indiana (Amazon/Anthropic), already operational with over 1 GW and set to exceed 2 GW; Colossus 1 and 2 in Memphis (xAI), with approximately 900 MW already operational across the two sites; Prometheus in Ohio (Meta), with around 1 GW due to come online during 2026; Fairwater, straddling Wisconsin and Atlanta (Microsoft), with the first phases due to come online in 2026 and $7.3 billion invested in the Wisconsin site alone.
In Europe, three examples of the largest AI campuses currently operational or nearing completion, with declared power capacity: Start Campus in Sines, Portugal, with the first building operational from 2025 and a second 240 MW facility due to come online this year; it is the only European campus with 1.2 GW of grid power already secured; Stargate Norway in Narvik (Nscale/Aker/OpenAI), with 230 MW and 100,000 GPUs planned by the end of 2026, expandable to 520 MW; Nebius in Mäntsälä, Finland, with 75 MW already operational and a new 310 MW AI factory under construction.
According to Giordani, the real bottleneck is neither capital nor GPUs: it is the electricity grid. In the United States, waiting lists for grid connections are 5–7 years long, and it is estimated that 30–50 per cent of the capacity planned for 2026 will be delayed until 2027–28; the American response involves on-site gas turbines, as seen in Memphis and Abilene. In Europe, the situation is worse: a 7–10-year wait in the main markets, compared with the 2 years needed to build a campus. In Dublin, data centres already account for 80 per cent of local electricity consumption; in Amsterdam, London and Frankfurt, the figure ranges from one-third to over 40 per cent. In 2024 alone, grid congestion cost the European Union 4.3 billion euros.
It is no coincidence that new projects are springing up where energy is abundant: Sines, Narvik, Finland, and Rostock itself – chosen by Schwarz precisely because of the availability of wind power in northern Germany. The situation for Europe is not encouraging: in the US, 1 GW campuses and larger are already well established, whilst on the Old Continent the largest operational plants are measured in hundreds of MW.
In short, the timeframe Lidl has set itself to reach 1 gigawatt (2045) is far too long!
What’s more, in Europe, apart from Lidl, there are no similar projects on the horizon:once again, Europe confirms all its technological lag behind the United States.
But there is another problem just round the corner, in addition to the issue of European delays: it is both environmental and political. Residents – even in the United States – who find themselves living in close proximity to data centres are increasingly opposed to these facilities.
And they are now making their opposition known openly.
In fact, Lidl has specified that “the projects envisage the exclusive use of renewable energy during normal operation and a closed-loop water-cooling system, which limits water consumption…”
But in some cases, data centres are not only accused of causing environmental damage but also of driving down the value of land and homes (in 2026, there were 140 coordinated protests across 42 US states ).
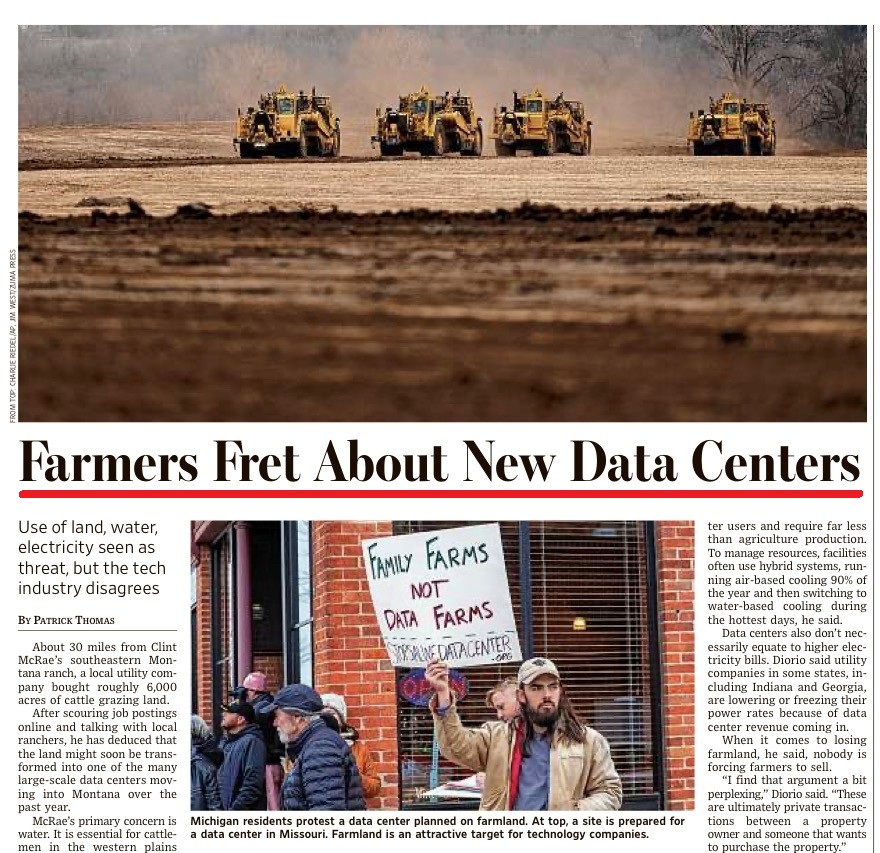
Meanwhile, American farmers are concerned (“to fret” = to worry) about data centres (The Wall Street Journal, July 2026). And they have good reason to be: agriculture is competing with data centres for a vital resource: water (the rush to build the world’s largest data centre has already forced Texas into recurring droughts).
On this topic, read also: How Big Tech is quietly trying to reshape the way pollution is reported.